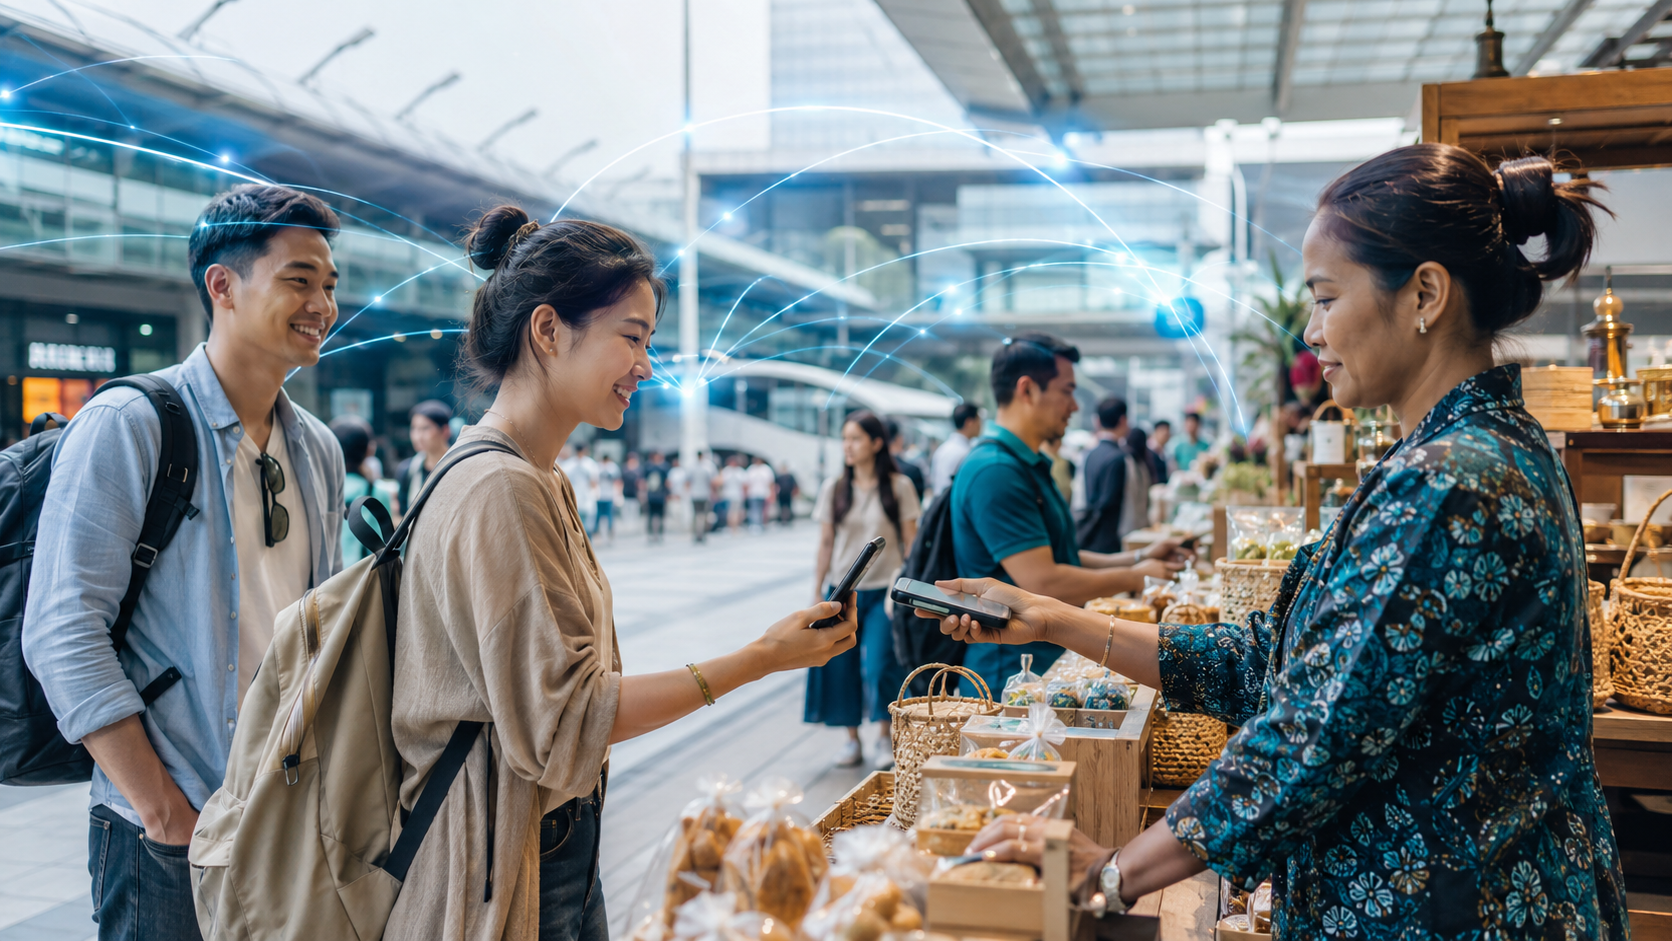
A payment experience can feel almost trivial: open an app, scan a code, confirm the amount, and continue with the day. Yet the simpler the experience becomes for the customer, the more coordination is usually happening behind the screen.
That contrast is becoming visible across Asia. On 26 August 2026, Bank Indonesia highlighted a new QR-code connection intended to make transactions more convenient, affordable, and faster. The development sits inside a broader regional movement toward interoperable payments. Indonesia's QRIS ecosystem had reached 65.77 million users by June 2026, according to figures cited by the government, while cross-border links are extending the usefulness of domestic payment rails beyond their original boundaries.
The interesting lesson is not only about QR codes. It is about what happens when a product stops being a feature and starts behaving like infrastructure.
Convenience is the visible layer, interoperability is the product
Customers do not want to understand settlement networks, currency conversion, participant rules, dispute handling, or message standards. They want to know whether the payment worked, how much it cost, and what to do if something went wrong.
For product teams, however, every one of those hidden elements is part of the experience. A cross-border payment must connect institutions with different systems, operating hours, risk rules, naming conventions, and customer expectations. The QR code is only the entry point. The actual product is the coordinated chain that moves from initiation to authentication, routing, conversion, confirmation, settlement, reconciliation, and support.
This is why interoperability should not be treated as a final integration task. It is a product capability that must be designed from the beginning.
A successful transaction is not the only journey
The happy path is easy to demonstrate. A traveller scans a merchant code, sees the amount, approves the payment, and receives confirmation. Real systems are defined by the exceptions around that path.
What if the merchant name displayed to the customer differs from the store sign? What happens when the exchange rate changes between initiation and confirmation? Which party owns a timeout? Can a duplicate request be detected across two networks? How quickly is a reversal reflected? Which language does the support team use? What evidence is available when the customer and merchant disagree?
These are not edge cases to postpone. At scale, small exception rates become daily operational volume. A product can report high technical availability while still creating confusion, manual reconciliation, or financial anxiety.
A mature payment product therefore needs acceptance criteria for failures as carefully as for success. The team should define error ownership, response codes, retry rules, customer messages, reconciliation windows, dispute evidence, and escalation paths before launch.
Standardisation creates room for innovation
Standards are sometimes described as constraints. In network products, they are often what makes innovation possible. Shared formats and rules reduce the number of custom connections each participant must build. They allow banks, wallets, merchants, and service providers to focus on differentiated experiences while relying on a common foundation.
But a standard is valuable only when its meaning is consistent. If two participants interpret the same status differently, the interface is technically connected but operationally fragmented. Governance must therefore cover versioning, certification, conformance testing, incident management, and change communication—not only documentation.
This is a familiar challenge in enterprise transformation. Integration succeeds when the teams agree not just on fields, but on business meaning, ownership, timing, and behaviour under stress.
Trust is built through small product decisions
Payments compress many dimensions of trust into a few seconds. The customer must trust the displayed merchant, amount, currency, rate, fee, and confirmation. The merchant must trust that a successful message will become settled funds. Participating institutions must trust each other's controls and operational commitments.
Clear confirmation language matters. So do visible exchange-rate information, consistent receipt details, privacy boundaries, accessible support, and honest status messages. A vague “something went wrong” response may protect the interface from technical detail, but it leaves the customer without a decision. Should they try again, use another method, or wait?
Good error design tells the user what is known, what is not yet known, and what action is safe. In financial products, that clarity is not cosmetic. It reduces duplicate payments, support demand, and loss of confidence.
What product teams can learn beyond payments
The same principles apply to many connected enterprise products.
First, design the ecosystem, not only the screen. Map every participant, handoff, source of truth, and service obligation.
Second, make business semantics explicit. “Completed,” “accepted,” “processed,” and “settled” may describe different states. Users and systems need definitions that do not shift between modules.
Third, treat reconciliation as part of the core journey. When multiple systems record the same event, teams need a method to detect and resolve differences.
Fourth, test realistic exceptions. Simulate latency, duplicate messages, partial outages, invalid identifiers, currency changes, and delayed confirmation. A system that works only when every dependency behaves perfectly is not production-ready.
Fifth, measure outcomes across the network. Transaction volume is useful, but teams should also monitor failure reasons, reversal time, dispute volume, support contacts, participant-level reliability, and the percentage of exceptions requiring manual intervention.
Infrastructure succeeds when it becomes boring
The strongest payment infrastructure eventually disappears into normal behaviour. People stop thinking about the network and simply expect it to work. Reaching that point requires patient coordination among regulators, banks, payment providers, merchants, operations teams, security teams, and product teams.
The strategic value of cross-border QR payments is therefore larger than a faster checkout for travellers. They demonstrate how digital ecosystems can reduce friction through common standards while preserving local participation. They also remind us that scale comes from reliable cooperation, not from a single impressive interface.
For Business Analysts and Product Managers, the opportunity is clear. The work is to translate a simple customer promise into precise rules, resilient integrations, understandable states, and accountable operations.
When the customer sees only one scan, the product team should see the whole system.
**Discussion:** Which hidden handoff in your product creates the most customer friction when it fails?
Sources
- [Bank Indonesia — official payment-system update, 26 August 2026](https://www.bi.go.id/en/default.aspx)
- [ANTARA — Indonesia pushes digital payments to transform national trade, 26 August 2026](https://en.antaranews.com/news/428609/indonesia-pushes-digital-payments-to-transform-national-trade)